Zero-Based Budgeting
Learn what zero-based budgeting is and how Zerosum helps you plan every dollar. A beginner's guide to ZBB.
Written By Pedro
Last updated 4 days ago
Zero-based budgeting plans every dollar of income before you spend it. Instead of looking back at where your money went, you decide where it goes in advance.
What is zero-based budgeting?
Zero-based budgeting (ZBB) budgets every dollar of income to a specific purpose before you spend it. The math is simple: Income − Budgeted = $0. Every dollar is accounted for, so nothing sits around undirected.
💡 Tip: Zero doesn't mean broke. A zero budget just means you've intentionally decided where every dollar goes, and savings is a perfectly valid job for your money.
The four principles
- Be intentional. Decide where your money goes in advance instead of wondering "where did it go?" at month-end.
- Stay flexible. Life changes, so move money between categories when it does. Your budget adapts to reality, not the other way around.
- Budget real money. Only budget money you have right now. Don't budget next week's paycheck until it arrives.
- Prioritize what matters. Pay essentials first (rent, food, utilities), then decide what to do with what remains.
Plan every dollar
The core rule: every dollar must have a purpose. That purpose can be any of these:
- Bills and necessities: rent, utilities, insurance, groceries
- Savings goals: emergency fund, vacation, car down payment
- Debt payoff: student loans, car payments, payoff plans
- Fun and lifestyle: entertainment, hobbies, dining out
ℹ️ Note: Savings and fun money are both valid jobs. ZBB is about intentional choices, not deprivation.
Understanding "Ready to Budget"
Ready to Budget is money you have that is not in a category yet. Your goal is to bring it to zero by budgeting it. Select the info icon next to it at the top of your budget to open Budget Calculation and see where the number comes from.
How it's calculated
Ready to Budget is what your budget accounts hold, minus what your categories already hold:
- + Budget account balances: your cash, plus any credit card with a positive balance
- − Available in categories: the total of the Available column, including hidden categories
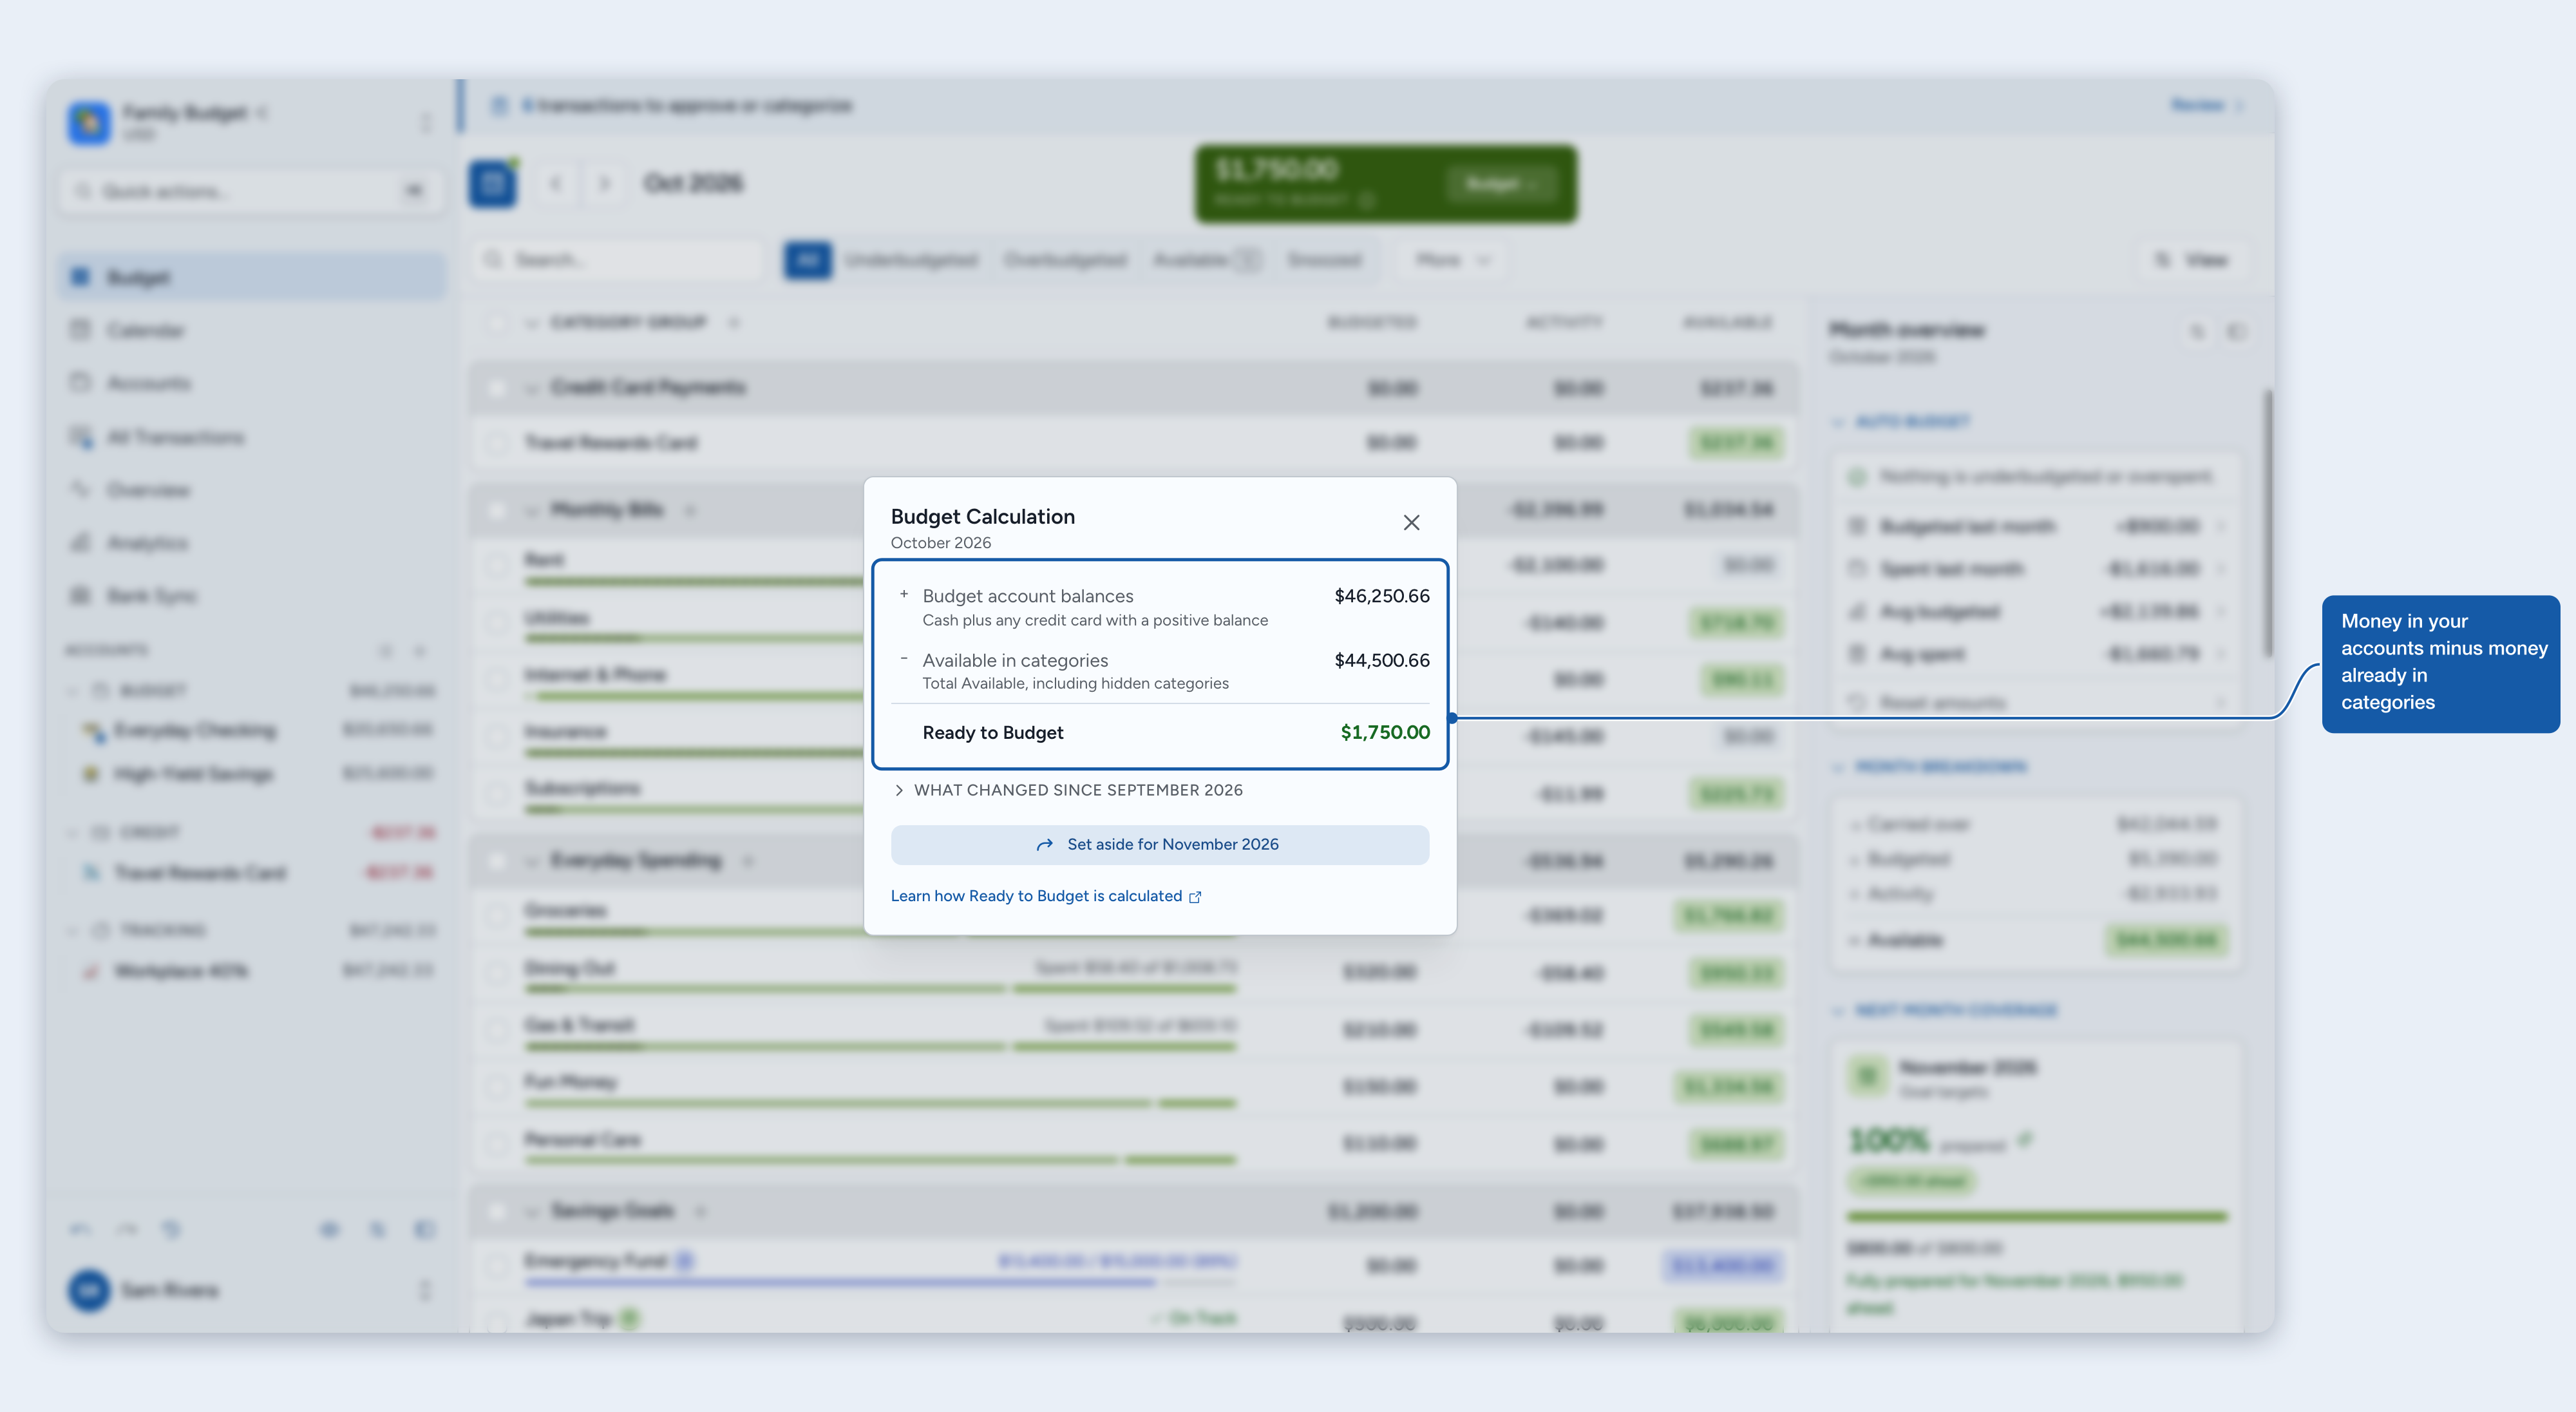
In this example the accounts hold $46,250.66 and the categories hold $44,500.66, so Ready to Budget is $1,750.00, still waiting to be budgeted.
Two more rows appear only when they apply:
- − Set aside for next month: income you set aside, plus any amount you set aside from Ready to Budget
- − Budgeted in later months: money from this month that you already budgeted in a later month
Credit-card debt never reduces Ready to Budget. It stays on the card, so it is left out of "Available in categories."
What changed since last month
Select What changed since in the same dialog to see how the month got to that number. The list always ends on the same Ready to Budget.
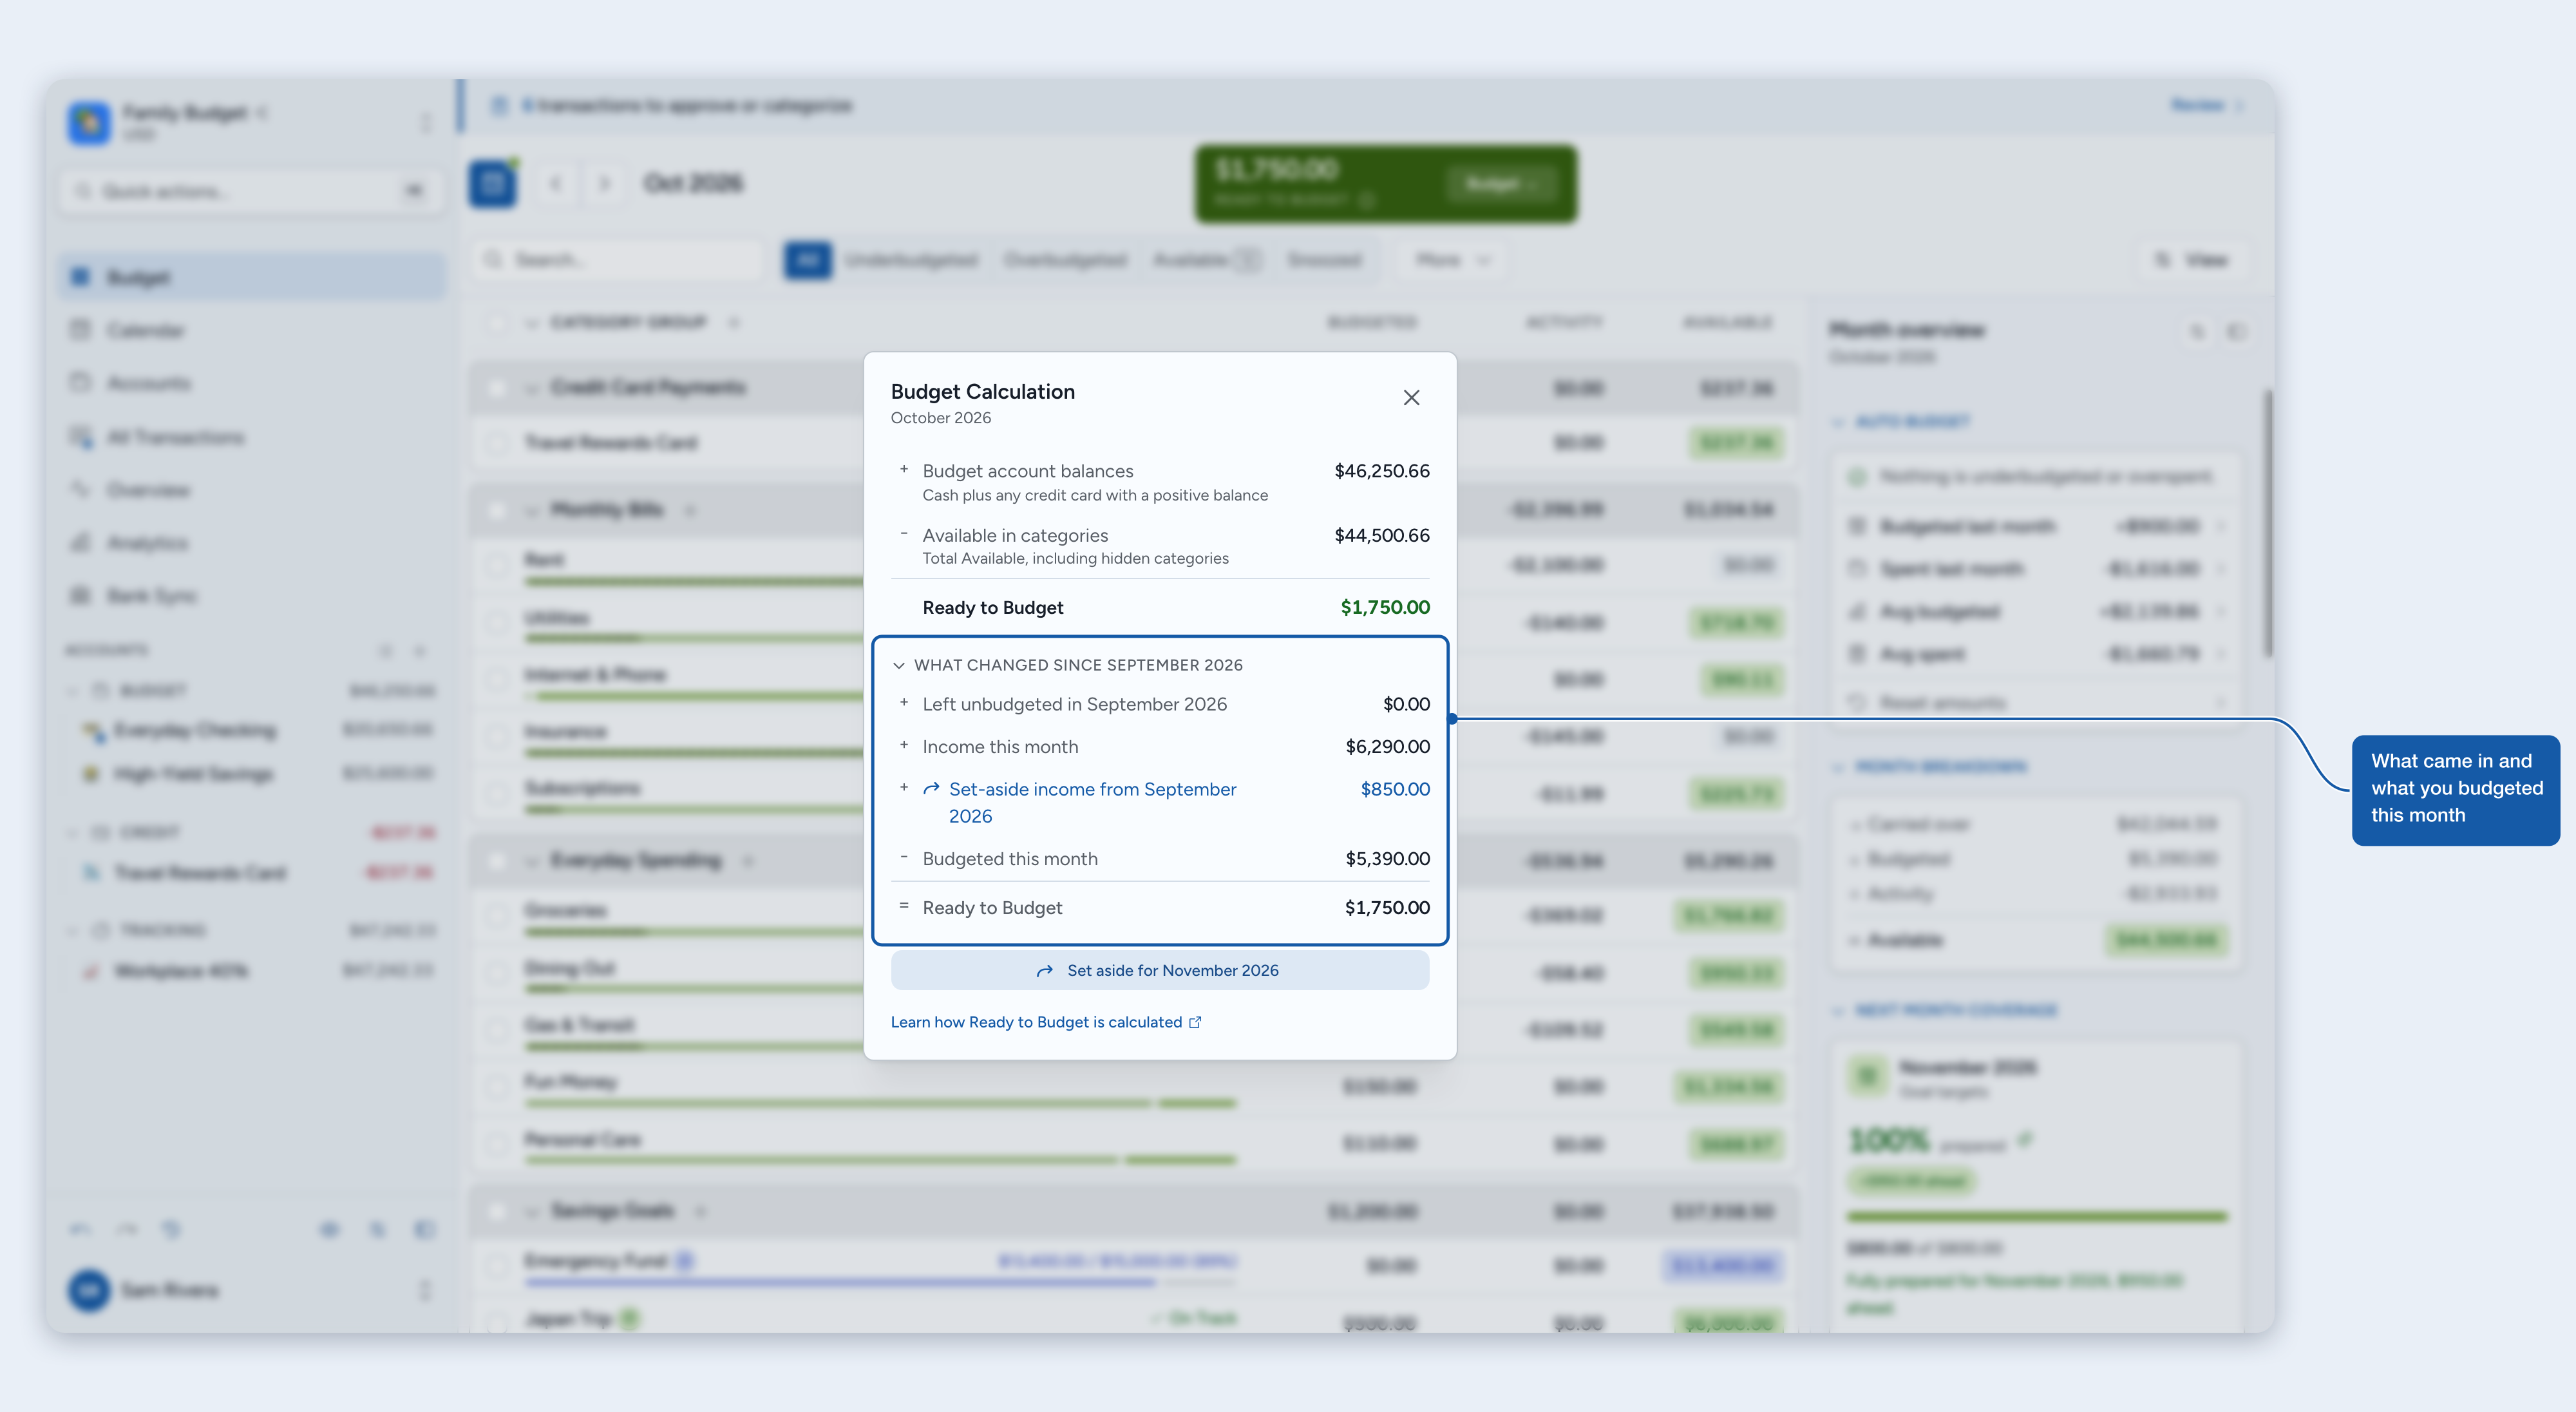
Most months show three rows:
- + Left unbudgeted in the previous month: Ready to Budget that the previous month did not budget. If you budgeted it in a later month, the previous month itself reads $0, and this row tells you what it shows
- + Income this month: money that came in on transactions categorized as Ready to Budget or an income category
- − Budgeted this month: what you budgeted to categories, minus anything you took back out
These rows appear only when they apply:
- − Moved out of Ready to Budget: money that left on a transaction categorized as Ready to Budget, such as a transfer to a tracking account. It is shown apart from income, so income is only what came in
- + Set-aside income from and + Set aside from Ready to Budget in the previous month, and − Set-aside income for and − Set aside from Ready to Budget for next month: money one month set aside for the next
- − Overspent last month: cash overspending from last month comes out of this month's Ready to Budget
- − Budgeted in later months: the same row as above
- Credit card credit: a change in the positive balance on a credit card, such as overpaying a card or receiving income on a card
- Other changes: transfers and adjustments that have no category
Where money comes in
- Starting balances when you set up accounts
- Income transactions categorized as Ready to Budget (paychecks, reimbursements, and so on)
- Money unbudgeted from categories or returned via auto-budget
What happens when you overspend
By default, a category you overspent with cash resets to zero next month, and the deficit reduces next month's Ready to Budget. The drag flows to your unbudgeted money rather than haunting the category.
Overspending a category you paid with a credit card is debt, not a cash shortfall. It stays on the card and never reduces Ready to Budget, this month or next. That's why the calculator leaves credit-card debt out of "Available in categories."
💡 Tip: Move money from another category to the overspent one within the same month and the drag never appears. You can also cover overspending retroactively by budgeting to the overspent category in a past month, which is neutral on your current Ready to Budget.
Prefer the deficit to stay on the category instead? Turn on Carry over negative balances in Settings > Budgeting.
Past months
Every month shows its real Ready to Budget, past months included. A past month whose leftover you already budgeted in a later month reads $0. A past month still holding money you never assigned keeps showing it, so you can go back and budget it. A month where you budgeted more than it had reads negative.
You can still budget or move money in any past month. Budgeting in an earlier month reduces what carries forward into every later month, so the number shown is exactly what's still safe to budget there.
Budgeting ahead and over-commitment
When you pre-fund categories in a future month, Zerosum counts that pre-funding against your current Ready to Budget, so you see what's actually still available to budget this month. If you commit more money to future months than you have, Ready to Budget goes negative: the signal that you're over-committed and need to unbudget from future months or wait for more income. The same math applies to every month from the current month forward. When you've budgeted more into future months than you have, the side panel on the current month tells you: the Plan Ahead section turns red for next month, lists every later month with the amount you budgeted there, and names the first later month whose Ready to Budget is negative; select a row to open that month. For next month, the sentence says when the shortfall comes from this month's overspending: cover the overspending instead.
ℹ️ Note: Setting income aside for next month doesn't pull money back to this month. That money belongs to next month, so budgeting it there isn't "budgeting ahead"; it's budgeting next month's own money, and this month stays at $0 rather than going negative.
Setting income aside for next month
Income you set aside for next month is still money you received this month, so it shows up in "Income this month" in the breakdown. A matching "Set aside for next month" row moves that amount out of this month's Ready to Budget and over to next month's. For the full walkthrough, see Set aside for next month.
What the colors mean
- Green (positive): money waiting to be budgeted
- Gray (zero): every dollar has a plan
- Red (negative): you've budgeted more than you have
⚠️ Warning: If Ready to Budget goes negative on the current month, select the Ready to Budget card and pick a category to cover the shortfall, or unbudget money from categories until it reaches zero or above.
Why it works
- Save more. Treat savings as a bill to yourself instead of a leftover.
- Less stress. Know exactly where every dollar goes, with no surprise overdrafts.
- Pay off debt faster. Intentionally allocate money to debt instead of paying the minimum.
- Spend guilt-free. When money is already budgeted for fun, you can spend it without second-guessing.
Where to next
Was this helpful?
Still need help? Share an idea